更多科大概覽

12月9日
2:00pm - 3:30pm
研討會, 演講, 講座

Recent machine learning techniques such as deep learning and reinforcement learning were built on specific assumptions of the underlying data generation process. Financial time series frequently do not satisfy these assumptions. In this talk, we discuss the possible problems if these techniques are applied blindly. The solutions to these problems are in general problem specific. However, some of the pain can be alleviated by combining recent machine learning techniques with more classical statistical and econometrics insights. We will discuss these probable solutions with examples.
12月9日
2:00pm - 3:30pm
地點
Room 2502 (Lifts 25/26)
講者/表演者
Prof. Jack CK WONG
Professor of Science Practice, HKUST
Professor of Science Practice, HKUST
主辦單位
Department of Mathematics
聯絡方法
付款詳情
對象
Alumni, Faculty and staff, PG students, UG students
語言
英語
其他活動
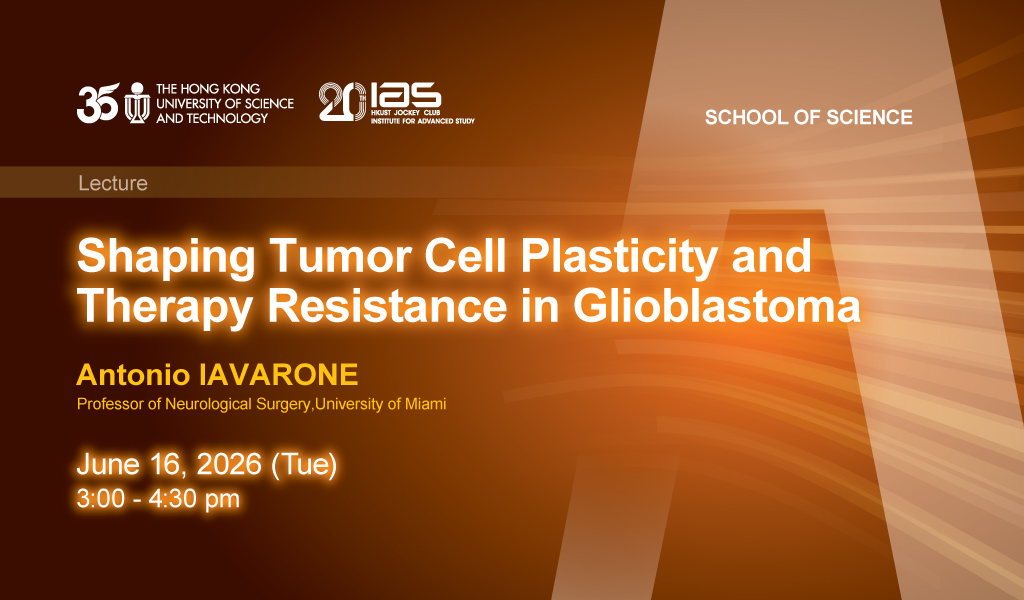
6月16日
研討會, 演講, 講座
IAS / School of Science Joint Lecture - Shaping Tumor Cell Plasticity and Therapy Resistance in Glioblastoma
Abstract
Tumor heterogeneity fueled by plasticity and genetic diversification of cancer cells is key to therapy failure of malignant glioma. The speaker's team implemented spatial and genetic p...