更多科大概覽
6月19日
3:00pm - 4:00pm
研討會, 演講, 講座

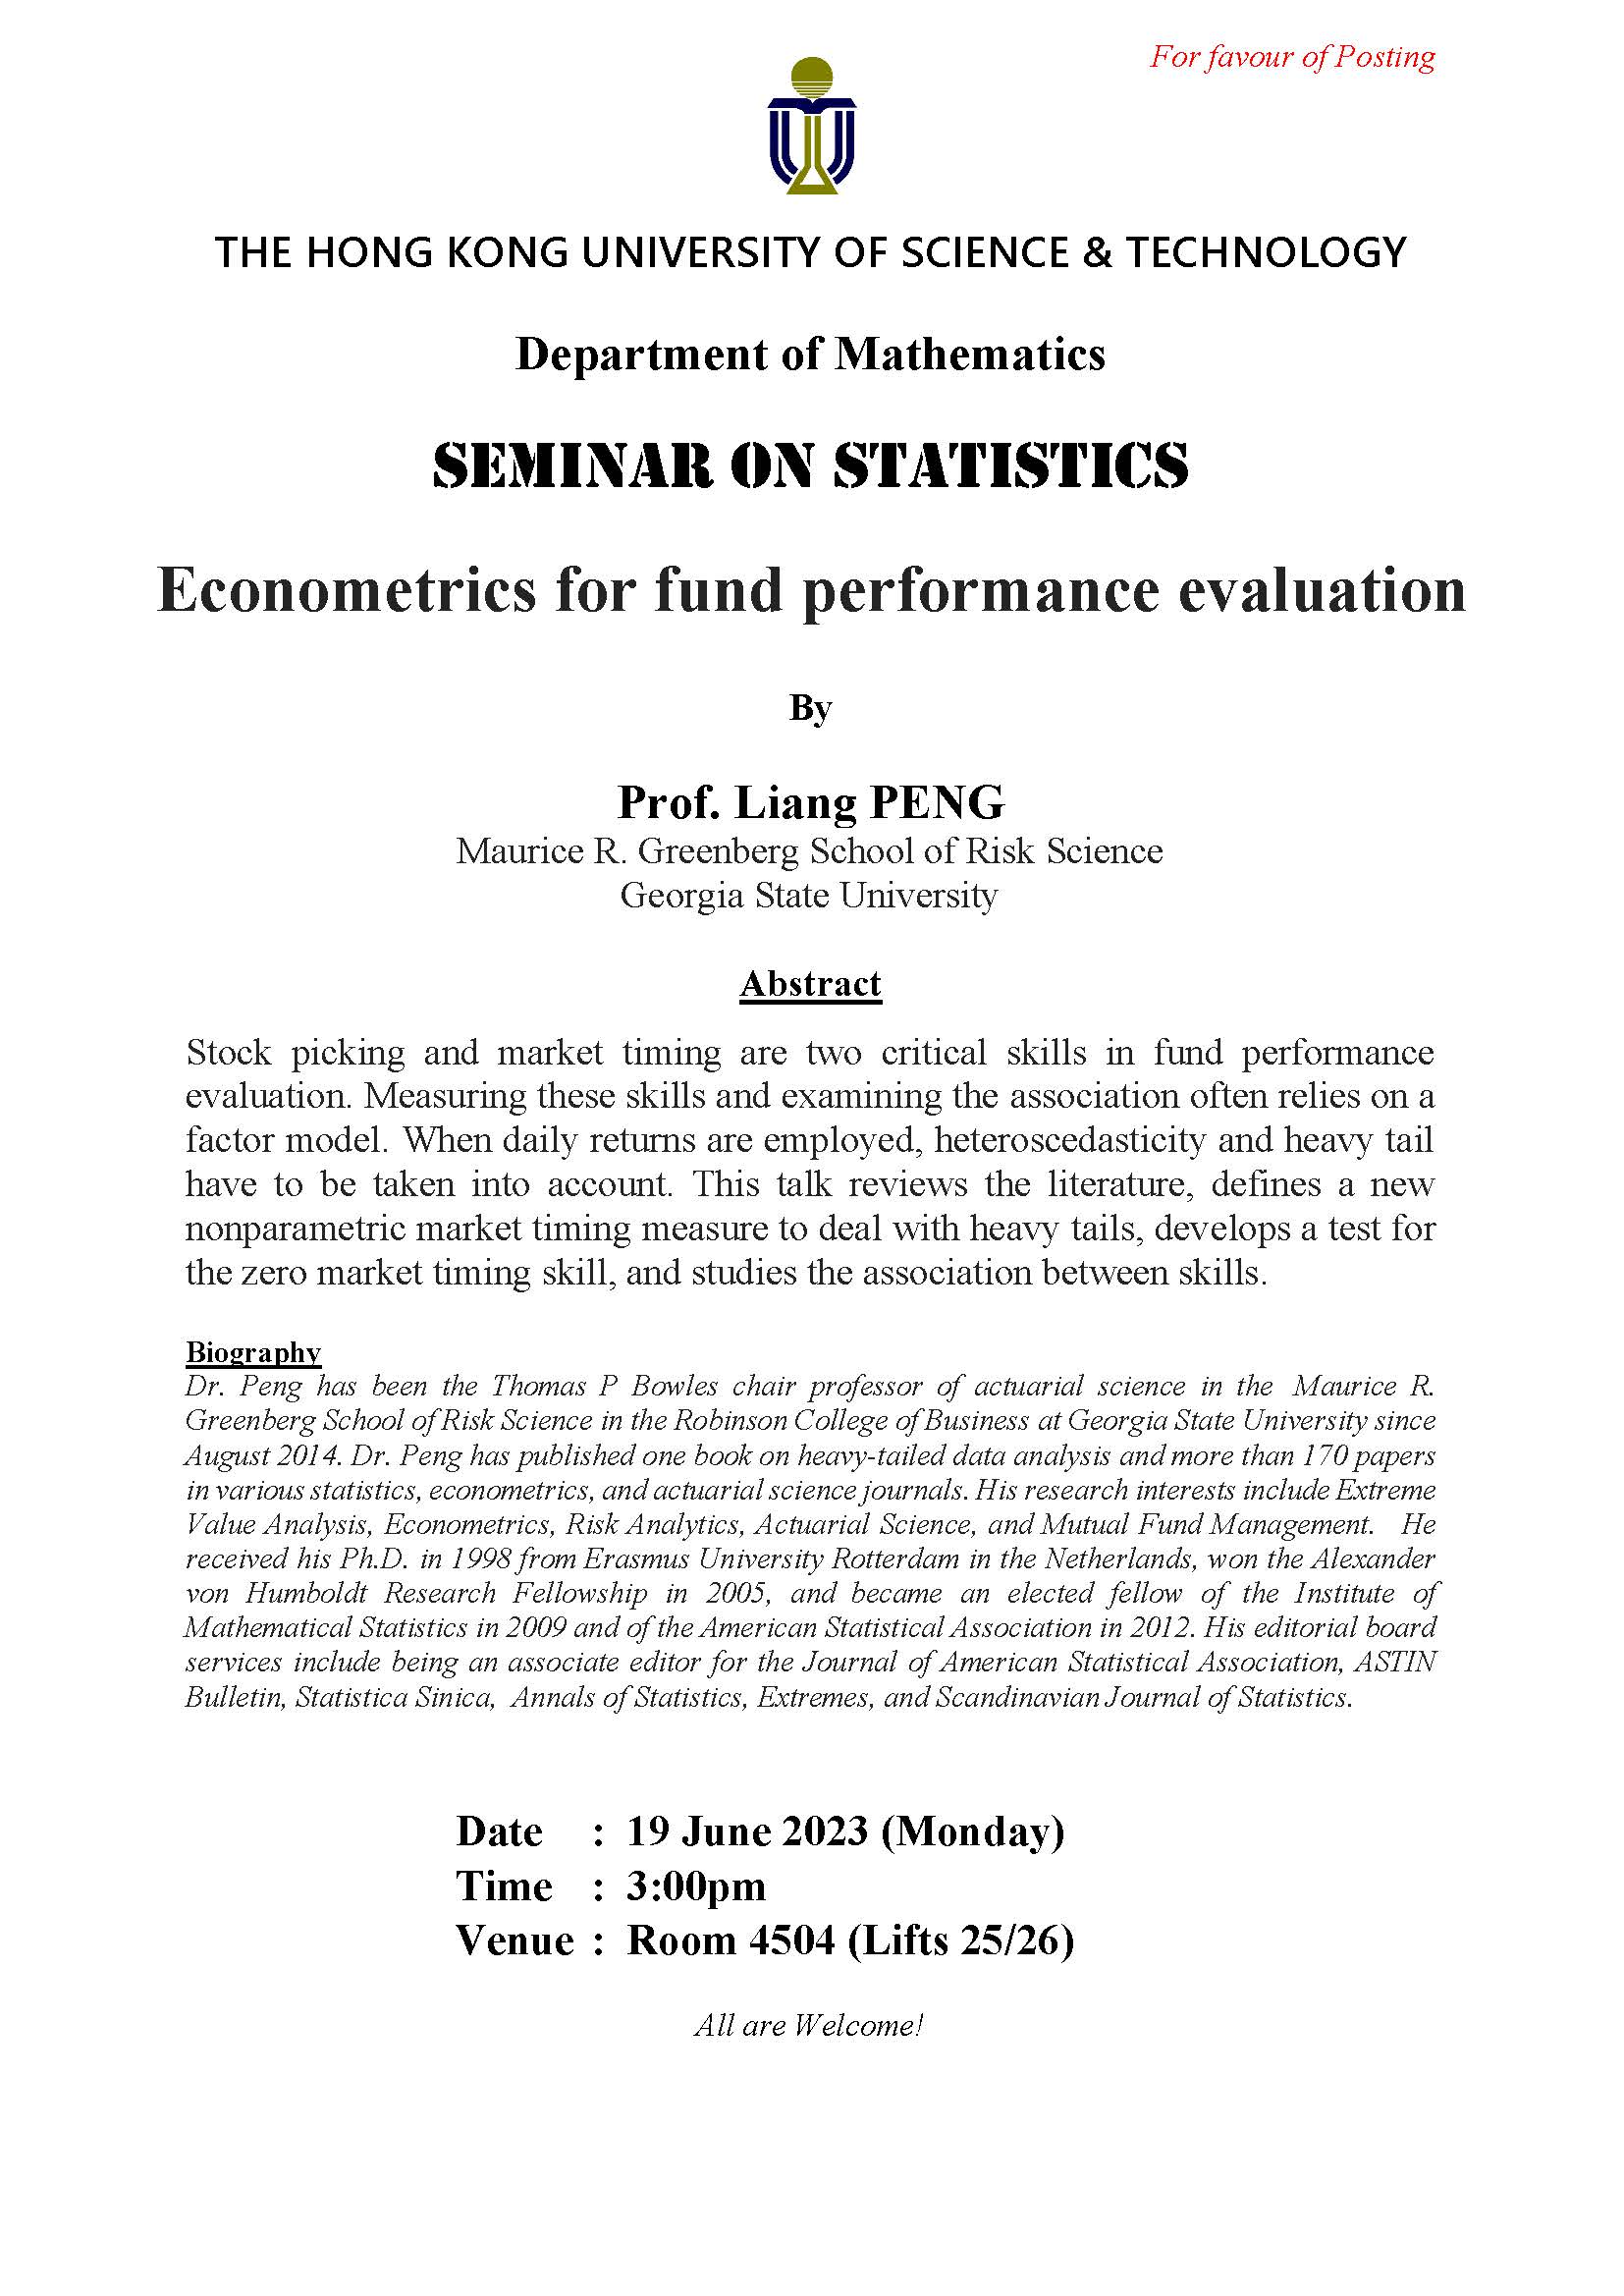
Stock picking and market timing are two critical skills in fund performance evaluation. Measuring these skills and examining the association often relies on a factor model. When daily returns are employed, heteroscedasticity and heavy tail have to be taken into account. This talk reviews the literature, defines a new nonparametric market timing measure to deal with heavy tails, develops a test for the zero market timing skill, and studies the association between skills.
6月19日
3:00pm - 4:00pm
地點
Room 4504 (Lifts 25/26)
講者/表演者
Prof. Liang PENG
Maurice R. Greenberg School of Risk Science, Georgia State University
Maurice R. Greenberg School of Risk Science, Georgia State University
主辦單位
Department of Mathematics
聯絡方法
付款詳情
對象
Alumni, Faculty and staff, PG students, UG students
語言
英語
其他活動
6月16日
研討會, 演講, 講座
IAS / School of Science Joint Lecture - Shaping Tumor Cell Plasticity and Therapy Resistance in Glioblastoma
Abstract
Tumor heterogeneity fueled by plasticity and genetic diversification of cancer cells is key to therapy failure of malignant glioma. The speaker's team implemented spatial and genetic p...