More about HKUST
19 Jun 2023
3:00pm - 4:00pm
Seminar, Lecture, Talk

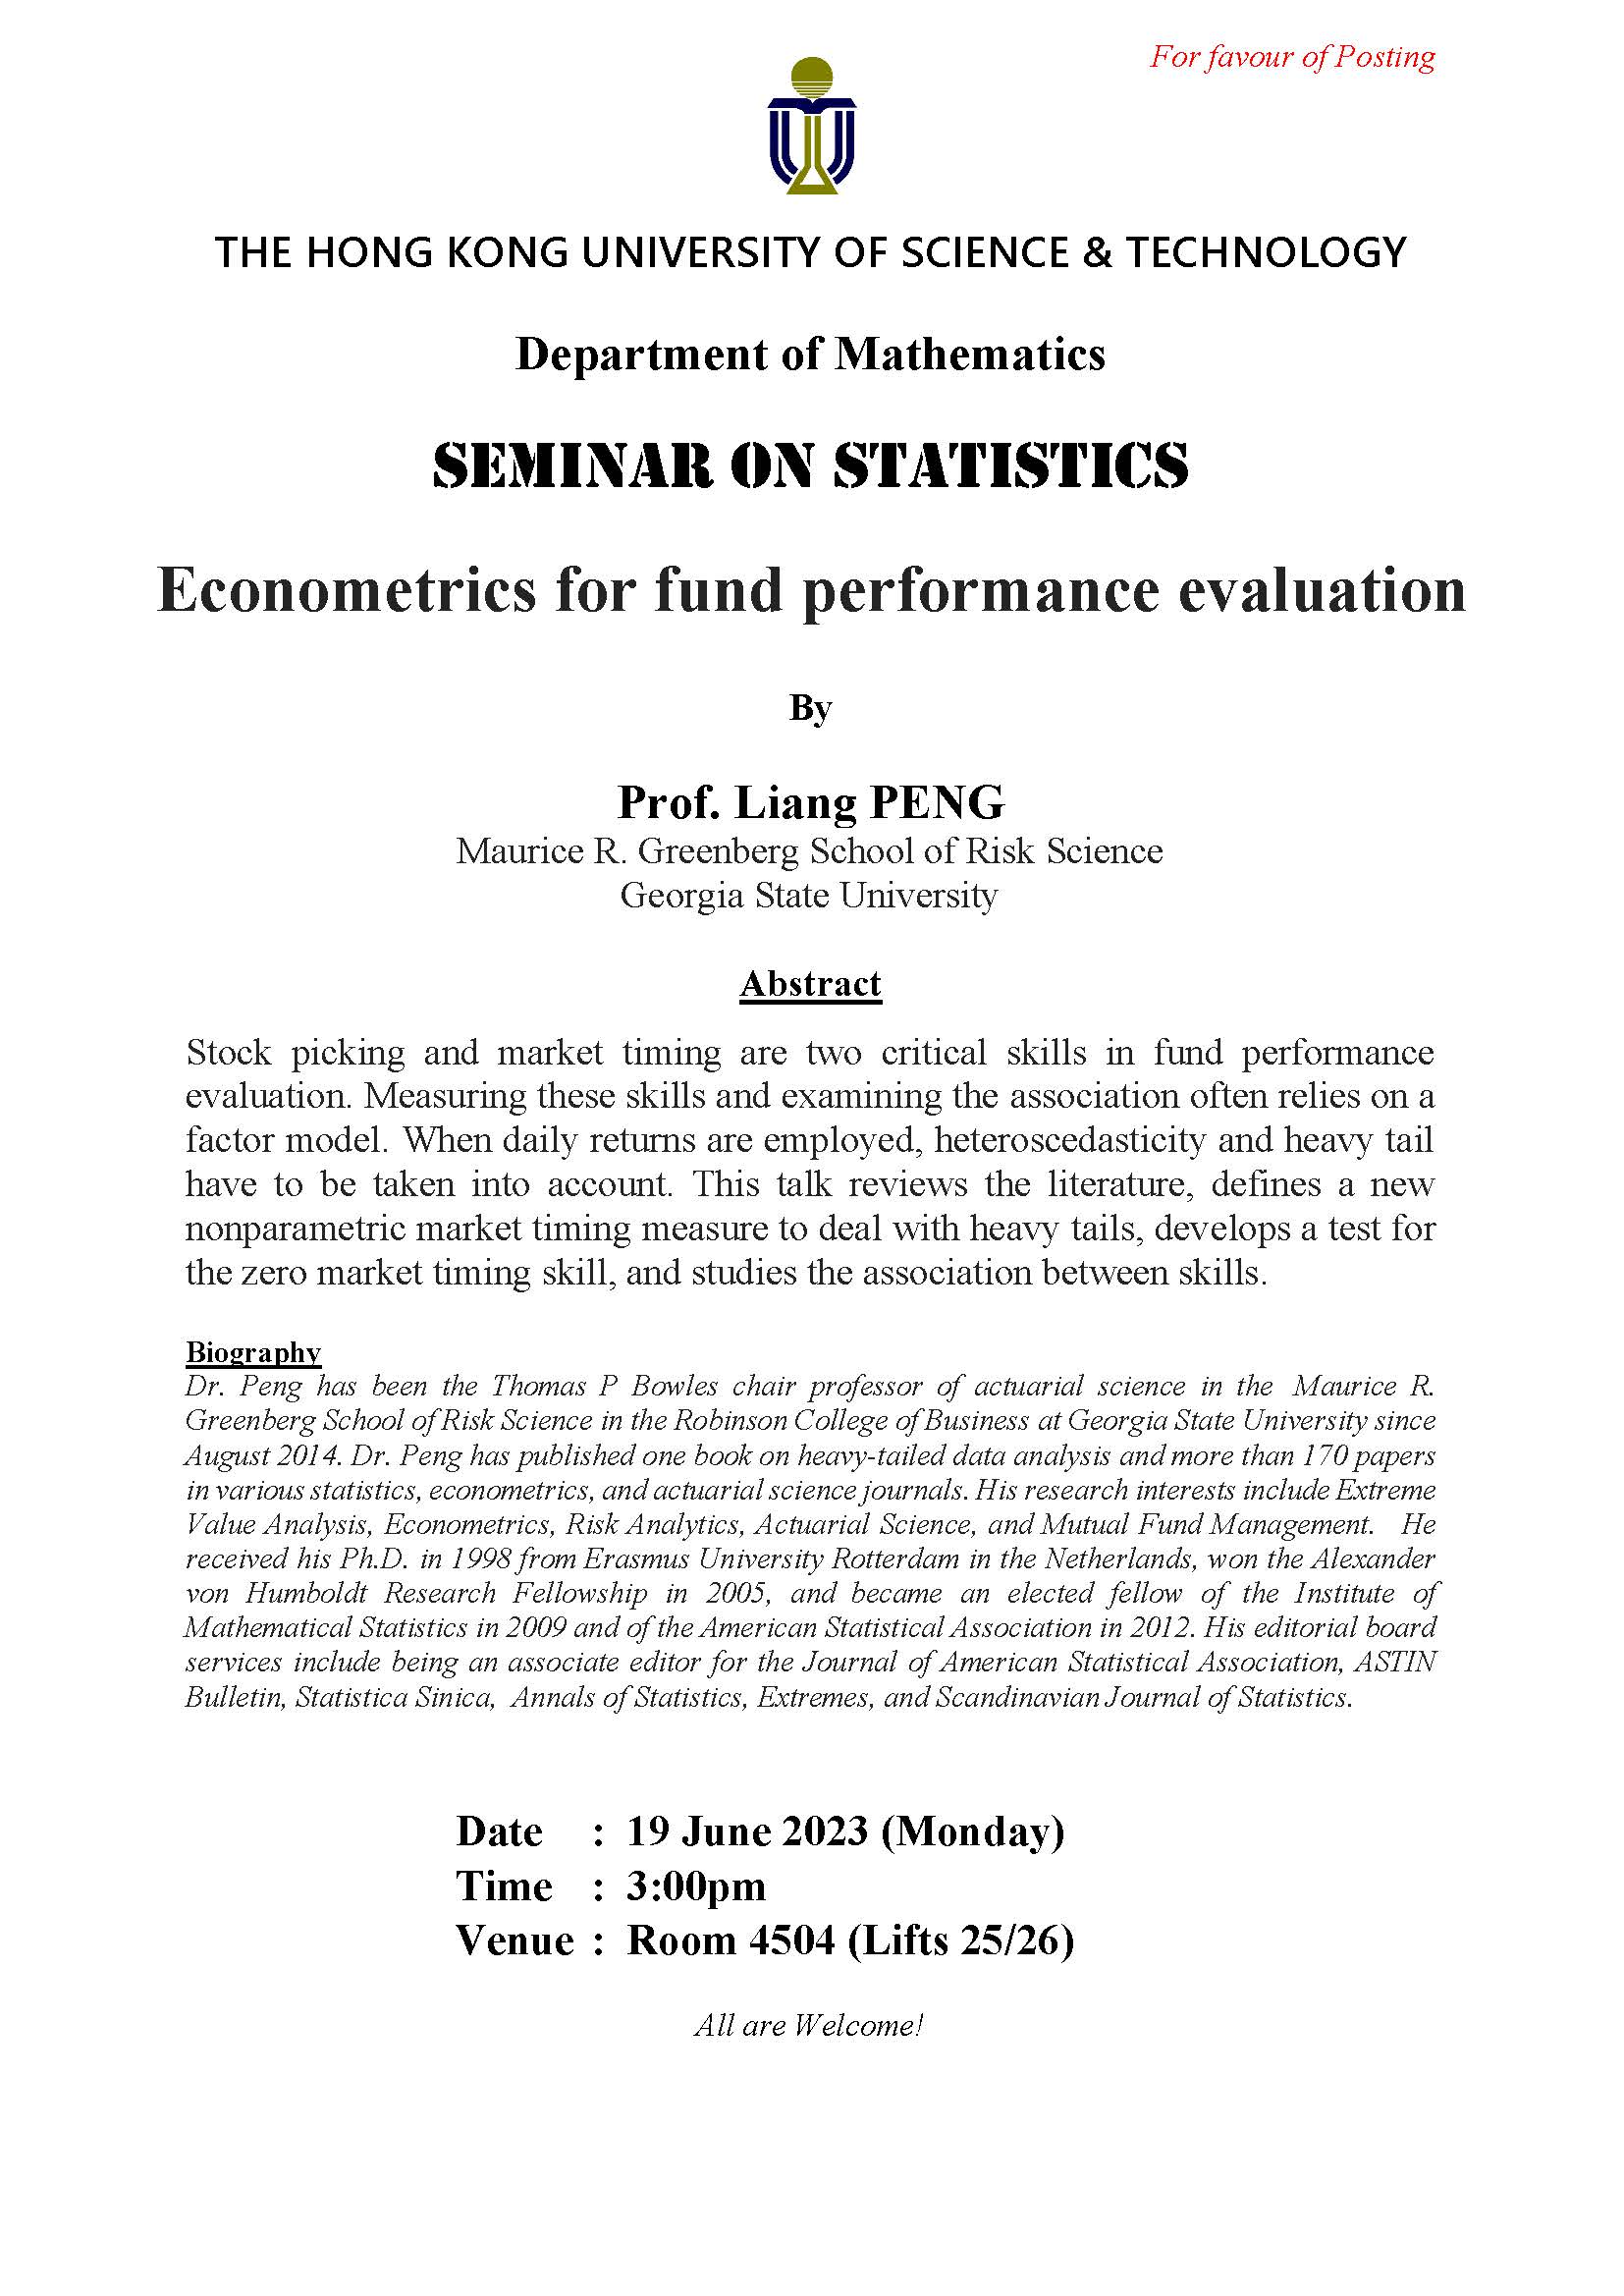
Stock picking and market timing are two critical skills in fund performance evaluation. Measuring these skills and examining the association often relies on a factor model. When daily returns are employed, heteroscedasticity and heavy tail have to be taken into account. This talk reviews the literature, defines a new nonparametric market timing measure to deal with heavy tails, develops a test for the zero market timing skill, and studies the association between skills.
19 Jun 2023
3:00pm - 4:00pm
Where
Room 4504 (Lifts 25/26)
Speakers/Performers
Prof. Liang PENG
Maurice R. Greenberg School of Risk Science, Georgia State University
Maurice R. Greenberg School of Risk Science, Georgia State University
Organizer(S)
Department of Mathematics
Contact/Enquiries
Payment Details
Audience
Alumni, Faculty and staff, PG students, UG students
Language(s)
English
Other Events
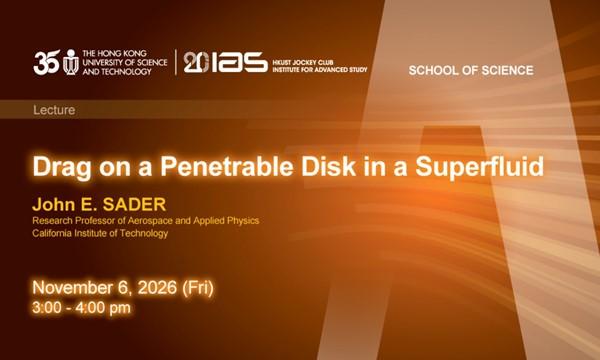
6 Nov 2026
Seminar, Lecture, Talk
IAS/ School of Science Joint Lecture - Drag on a Penetrable Disk in a Superfluid
Abstract
The motion of a body through a superfluid can generate phenomena distinct from a normal viscous fluid. This includes the absence of drag below a critical body speed with the shedding o...
16 Jun 2026
Seminar, Lecture, Talk
IAS / School of Science Joint Lecture - Shaping Tumor Cell Plasticity and Therapy Resistance in Glioblastoma
Abstract
Tumor heterogeneity fueled by plasticity and genetic diversification of cancer cells is key to therapy failure of malignant glioma. The speaker's team implemented spatial and genetic p...