更多科大概览
3月16日
4:00pm - 5:00pm
研讨会, 演讲, 讲座

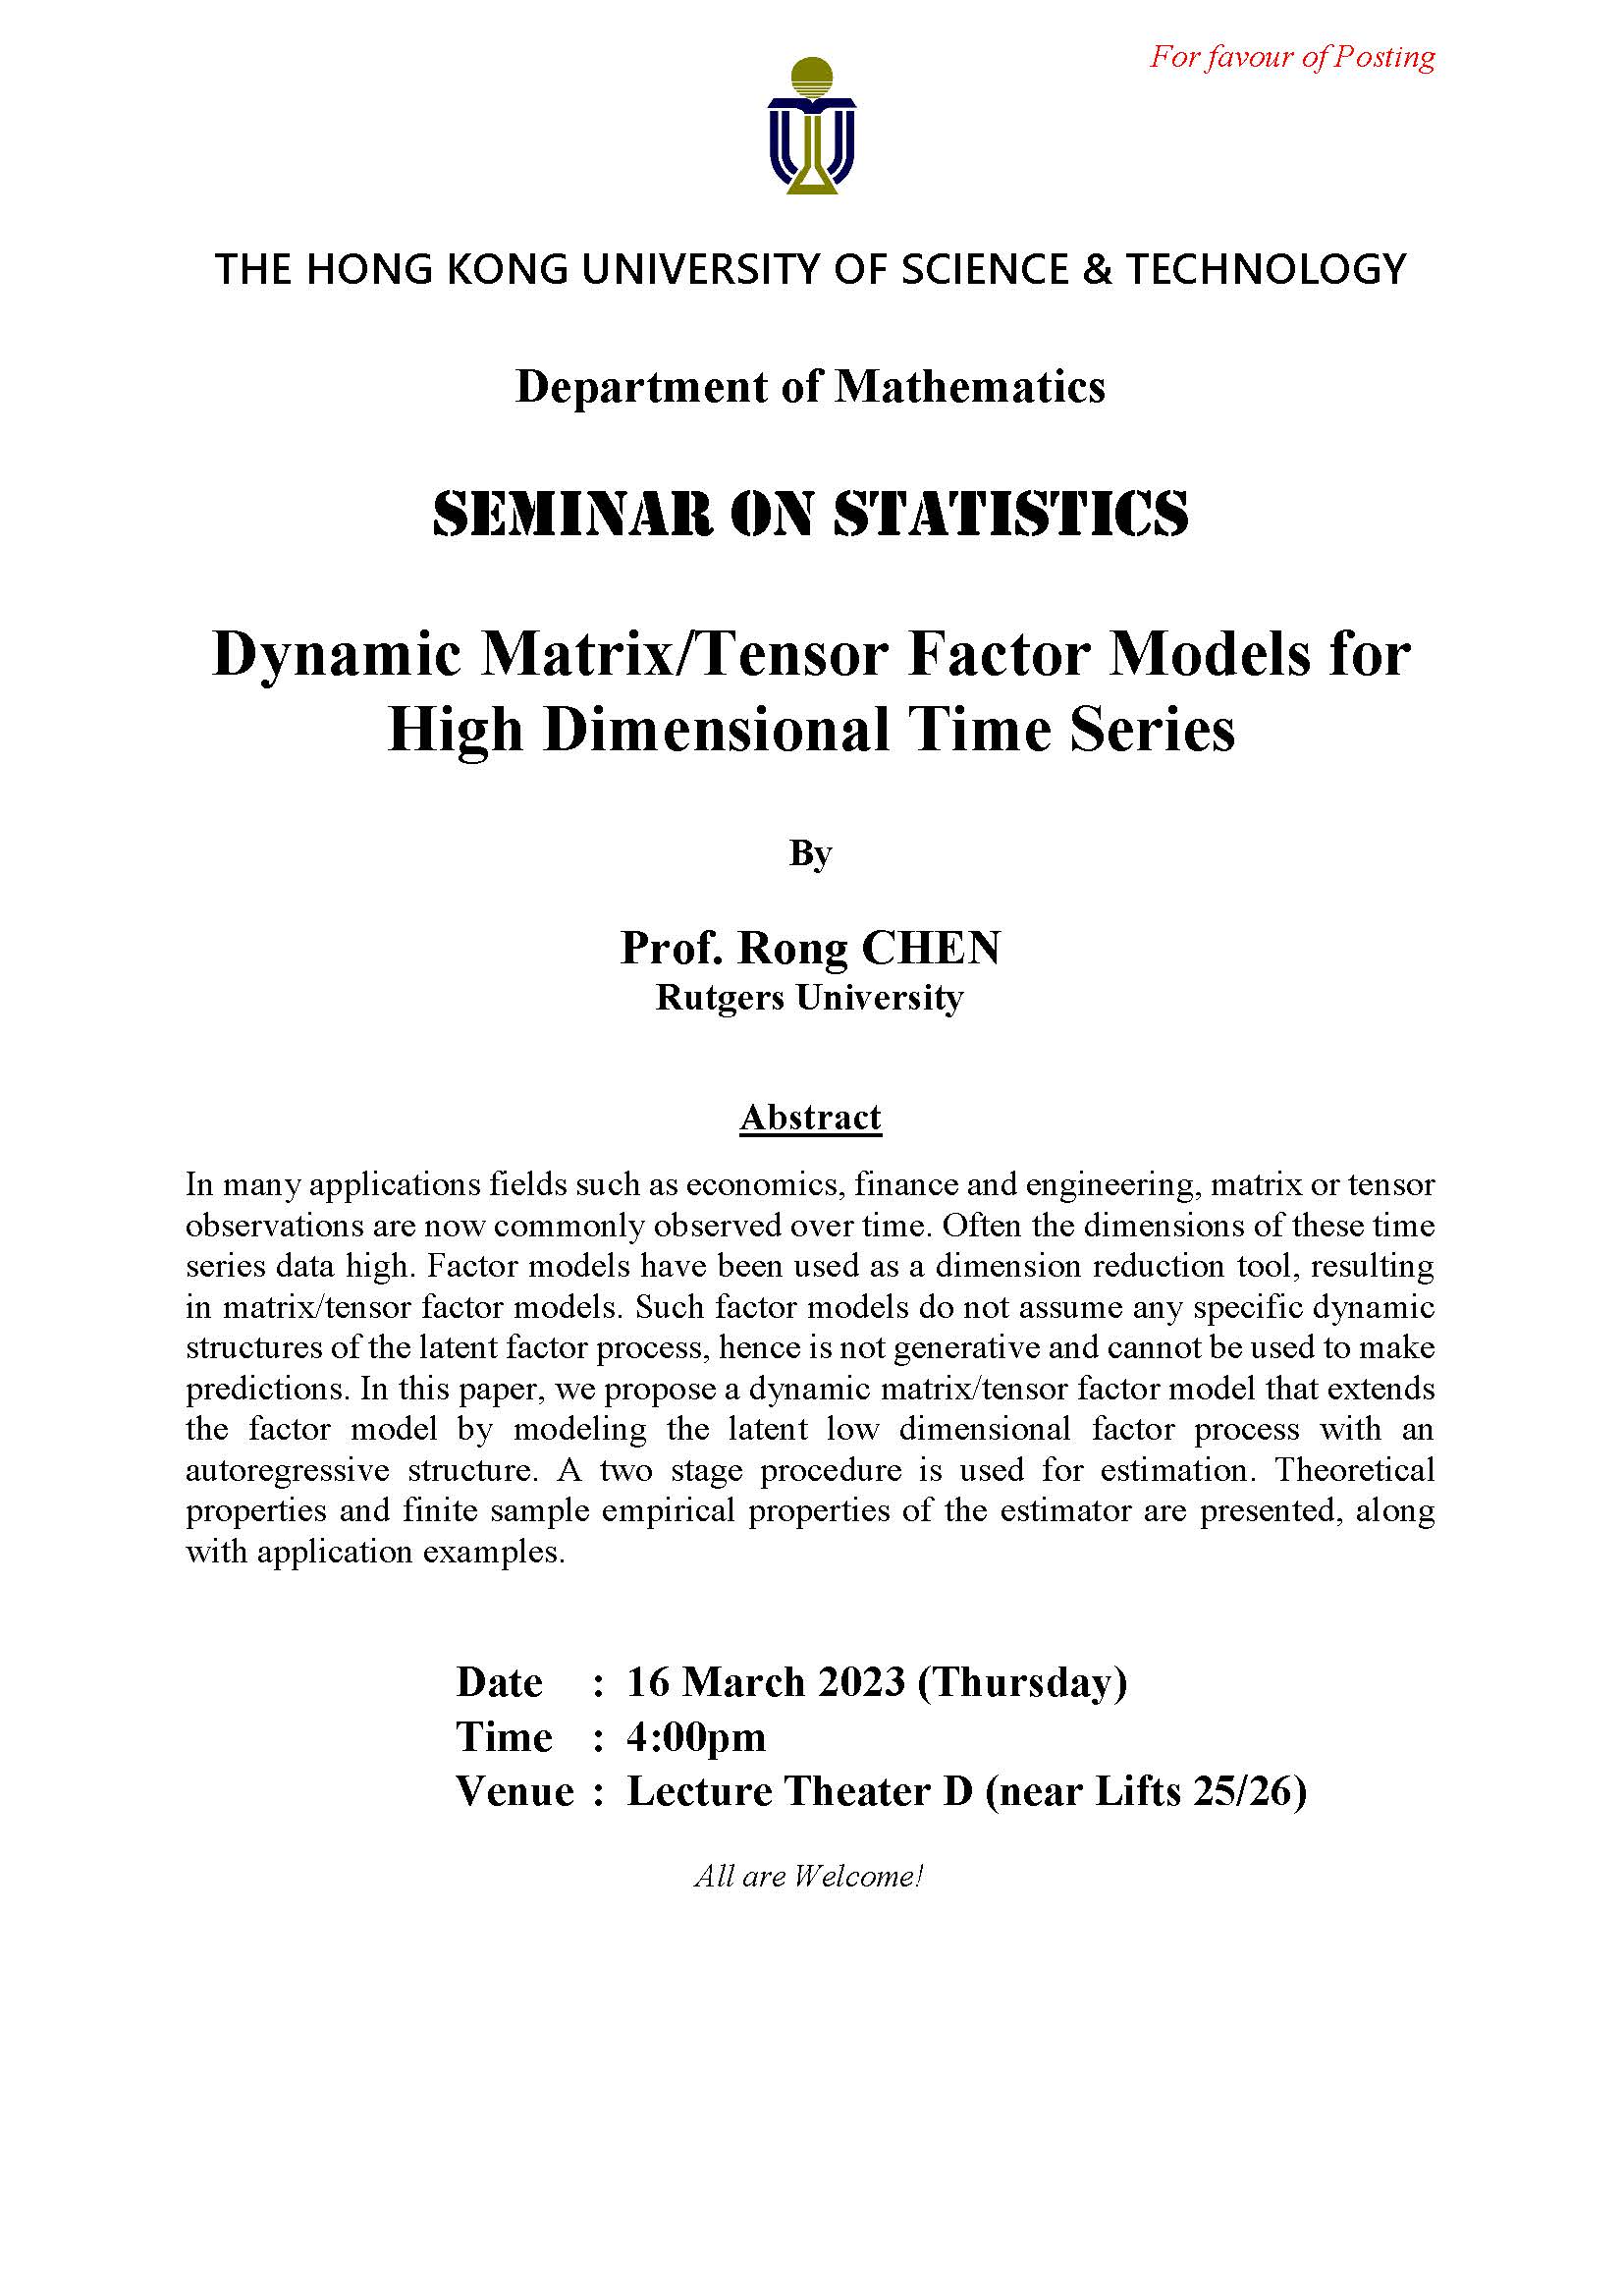
In many applications fields such as economics, finance and engineering, matrix or tensor observations are now commonly observed over time. Often the dimensions of these time series data high. Factor models have been used as a dimension reduction tool, resulting in matrix/tensor factor models. Such factor models do not assume any specific dynamic structures of the latent factor process, hence is not generative and cannot be used to make predictions. In this paper, we propose a dynamic matrix/tensor factor model that extends the factor model by modeling the latent low dimensional factor process with an autoregressive structure. A two stage procedure is used for estimation. Theoretical properties and finite sample empirical properties of the estimator are presented, along with application examples.
3月16日
4:00pm - 5:00pm
地点
Lecture Theater D (near Lifts 25/26)
讲者/表演者
Prof. Rong CHEN
Rutgers University
Rutgers University
主办单位
Department of Mathematics
联系方法
付款详情
对象
Alumni, Faculty and staff, PG students, UG students
语言
英语
其他活动
6月16日
研讨会, 演讲, 讲座
IAS / School of Science Joint Lecture - Shaping Tumor Cell Plasticity and Therapy Resistance in Glioblastoma
Abstract
Tumor heterogeneity fueled by plasticity and genetic diversification of cancer cells is key to therapy failure of malignant glioma. The speaker's team implemented spatial and genetic p...